On October 28, 2026, the Bank of Canada raised its policy interest rate by a quarter point, to 2.50%. This rate hike is the Bank’s first increase since July 2023, and in its announcement the Bank said it may need to raise rates further to keep inflation in check. The next scheduled decision is December 9, 2026.
If you’re planning a move in the next year, or your mortgage is coming up for renewal, you’re probably wondering what this means for you. The short answer: a quarter point isn’t a crisis, but it does change the math. Here’s how I’d think about it, depending on where you sit.
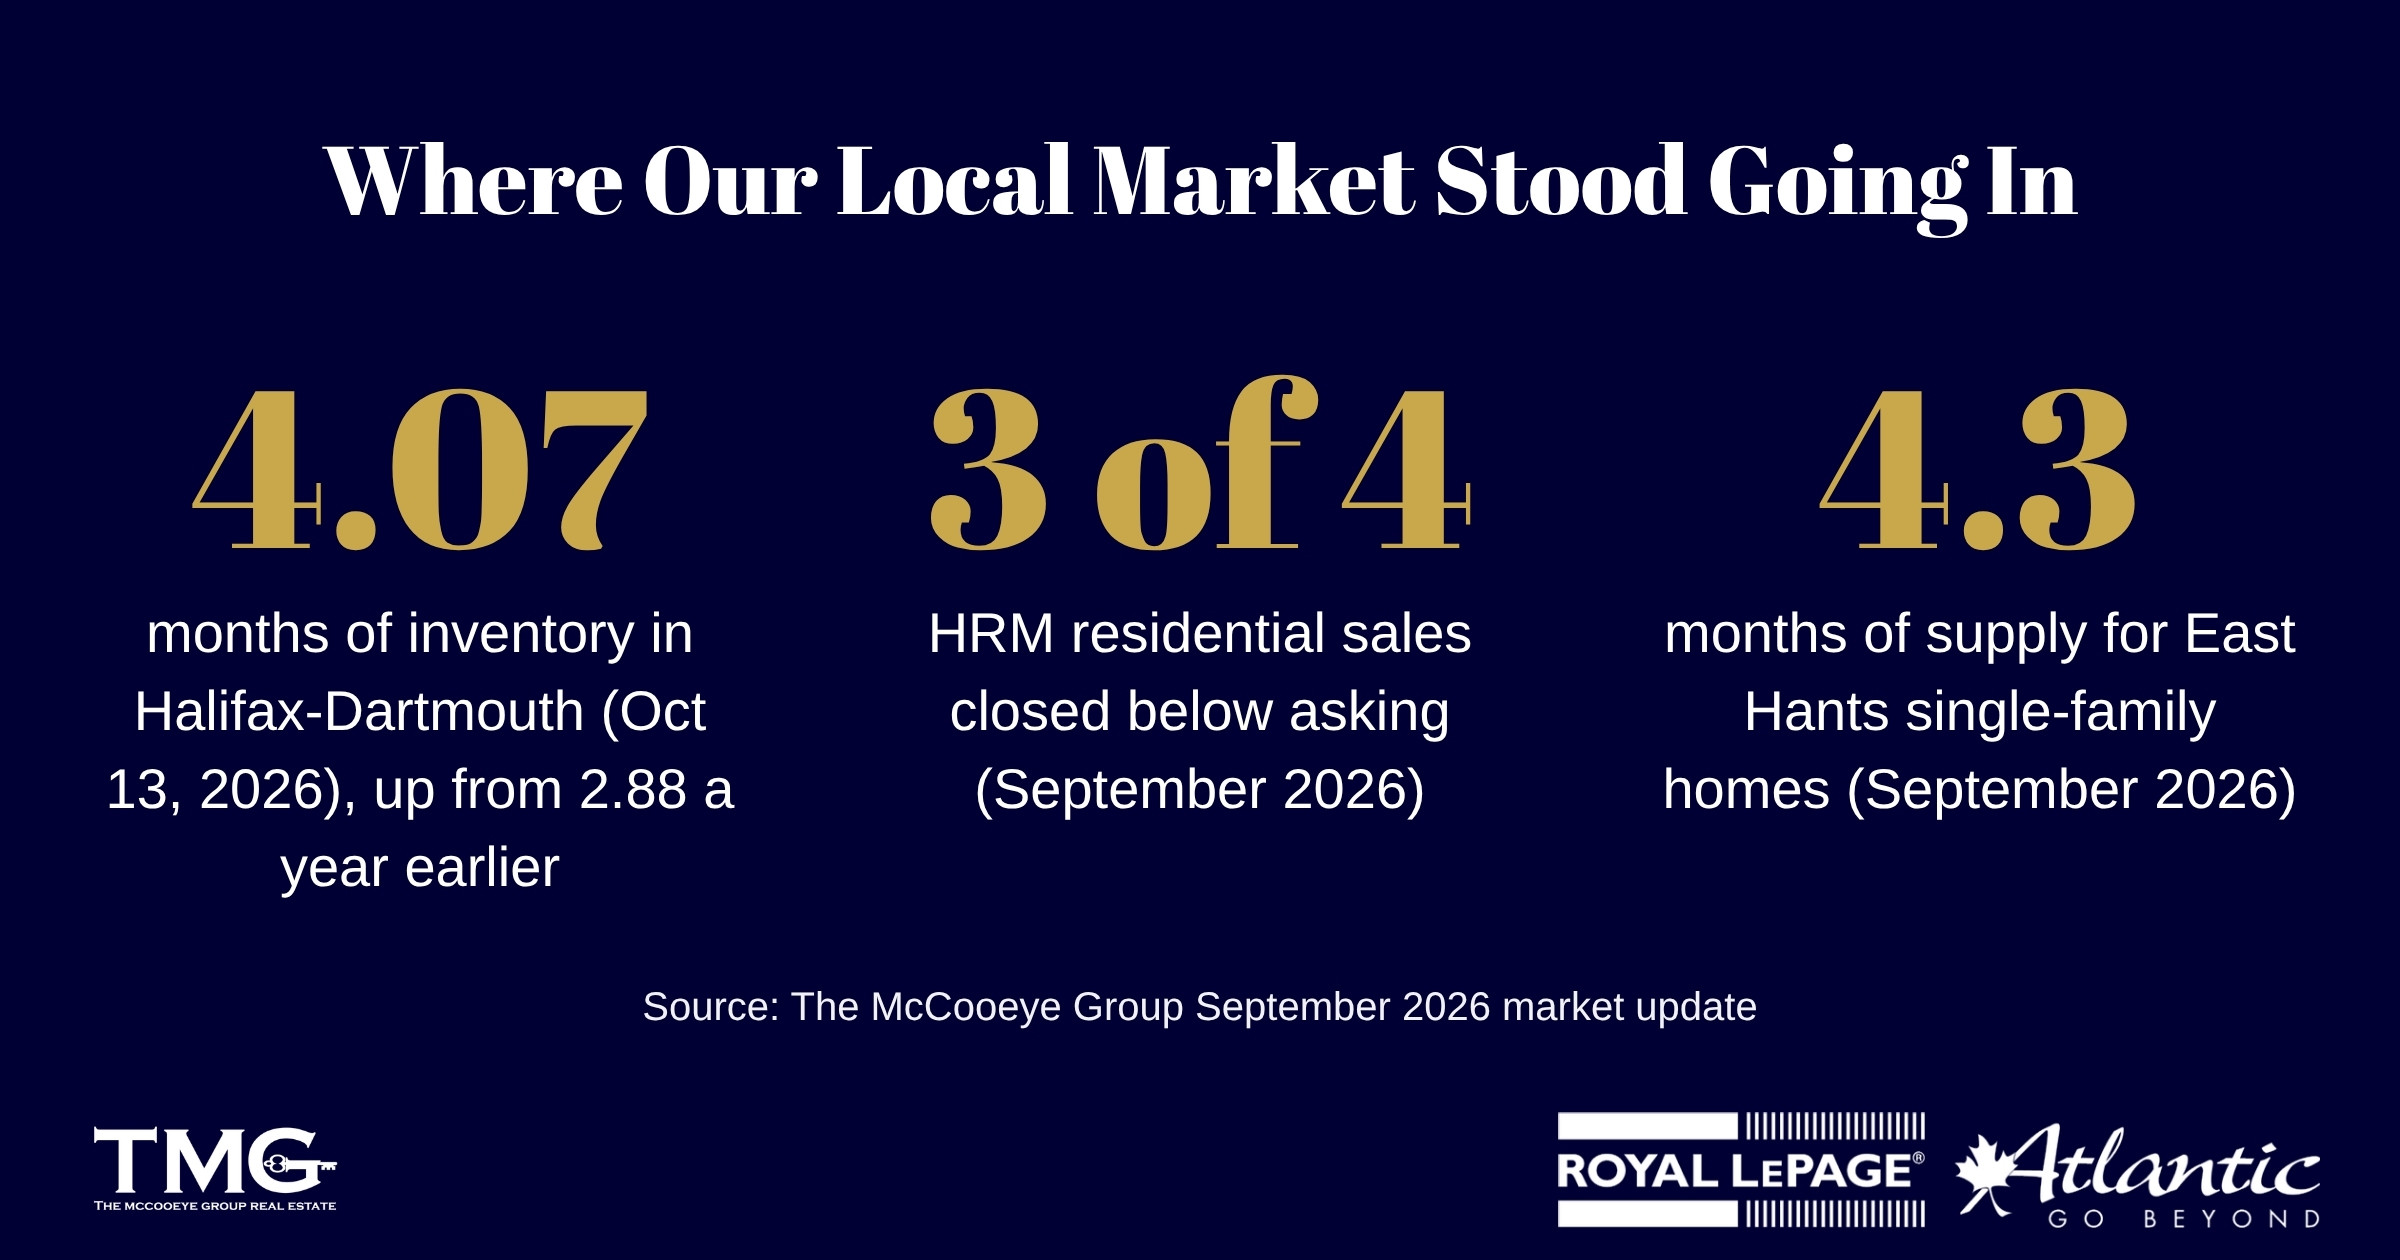
Where Our Local Market Stood Going In
It helps to remember that HRM and East Hants were already more balanced before this hike. In my September 2026 market update, I noted that as of October 13, 2026 there were 4.07 months of residential inventory in the Halifax-Dartmouth region, up from 2.88 on the same date in 2025. In September 2026, roughly three out of four HRM residential sales closed below asking. In East Hants, single-family months of supply was 4.3 in September 2026.
In plain terms, buyers already had more choice and more time. A rate increase adds a cost consideration on top of that, and it rewards people on both sides who plan ahead.
If You’re Buying
1. Get, or refresh, your pre-approval now
Most lenders will hold a pre-approved rate for a set period, often somewhere around 90 to 120 days. If rates move again, that hold can protect you. Ask your lender exactly how long the hold lasts and what conditions apply.
2. Re-run your numbers
Higher rates mean a higher monthly payment. And because you have to qualify at a rate above your actual contract rate under the federal mortgage stress test, your maximum approval may come down a little too. Know the number you’re comfortable paying each month, not just the most a lender will approve.
3. Talk fixed vs. variable with a mortgage professional
Variable rates follow your lender’s prime rate, which moves with the Bank of Canada. Fixed rates are driven more by bond yields. Neither is automatically the right call. It depends on your budget, how long you plan to stay, and how comfortable you are with your payment changing.
4. Keep your protections in place
With more homes to choose from, conditions for financing and a home inspection are reasonable to include, and so are well and septic inspections on rural properties around Enfield, Elmsdale, Lantz, Shubenacadie and the rest of East Hants. Don’t feel pressured to waive them.
5. Budget for the full cost of closing
Beyond your down payment, plan for deed transfer tax (the rate is set by each municipality), legal fees, inspections and adjustments. Your lender, lawyer and I can help you put realistic numbers to each one.
If You’re Selling
1. Price for today’s buyer
Buyers’ budgets just got a little tighter. A home priced in line with current comparable sales gets the attention; one priced off last year’s numbers tends to sit, and then chase the market down with price reductions.
2. Make it easy to say yes
Buyers with a rate hold have a reason to act before it expires. Clean, well-lit, well-photographed listings, a pre-listing inspection where it makes sense, and easy showing access all help you catch those motivated buyers.
3. Think beyond price
A flexible closing date, included appliances, or other reasonable terms can sometimes bridge a gap without cutting your price. Decide ahead of time what matters most to you.
4. If you’re buying and selling, plan the sequence
Bridge financing and carrying two properties both cost more when rates rise. Let’s map out your timing, and your financing options, before you list.
If Your Mortgage Is Up for Renewal
Start early. Many lenders will let you look at renewal options several months ahead of your term ending, and shopping around is worth the effort. Don’t automatically sign the first renewal offer that arrives in the mail. Ask a mortgage professional to compare it against other lenders, and ask whether switching lenders would require you to requalify. If you’re thinking of moving within a few years anyway, factor that into the term you choose.
The Bottom Line on the Rate Hike
A higher rate doesn’t change the fundamentals of why people want to live in HRM and East Hants, but it does reward preparation. Buyers who know their numbers and sellers who price realistically are still getting results in today’s more balanced market.
Every situation is different, and I’m not a mortgage advisor, so I always recommend speaking with your lender or mortgage broker about your specific financing. What I can do is show you what these changes mean for the homes and neighbourhoods you’re looking at, or what your home could sell for today. Give me a call at (902) 225-0892 or reach out to The McCooeye Group. I’m always happy to talk it through, no pressure.
Data Sources
- Bank of Canada, policy interest rate announcement, October 28, 2026 (rate raised 25 basis points to 2.50%; next scheduled decision December 9, 2026). bankofcanada.ca
- Royal LePage Atlantic “Weekly Stats Residential,” October 13, 2026: Paragon MLS®, HD Region, residential. Months of inventory as of October 13, 2026 and the same date in 2025.
- Royal LePage Atlantic “September Stats” summary: MLS® data for HD Region sold residential listings, September 2026 (sales relative to list price).
- NSAR Local Market Update, 105-Hants County East, September 2026 (single family). Current as of October 3, 2026. Data from the Nova Scotia Association of REALTORS®; report by ShowingTime Plus.
Local figures are from the most recent reports available at the time of writing (September 2026 and a weekly snapshot dated October 13, 2026); October 2026 statistics were not yet available. This post is general information, not mortgage, legal or financial advice.
By Don McCooeye, CD, BA, MA, SRES, CIPS | Royal LePage Atlantic
Keep Reading
More Resources From
The McCooeye Group